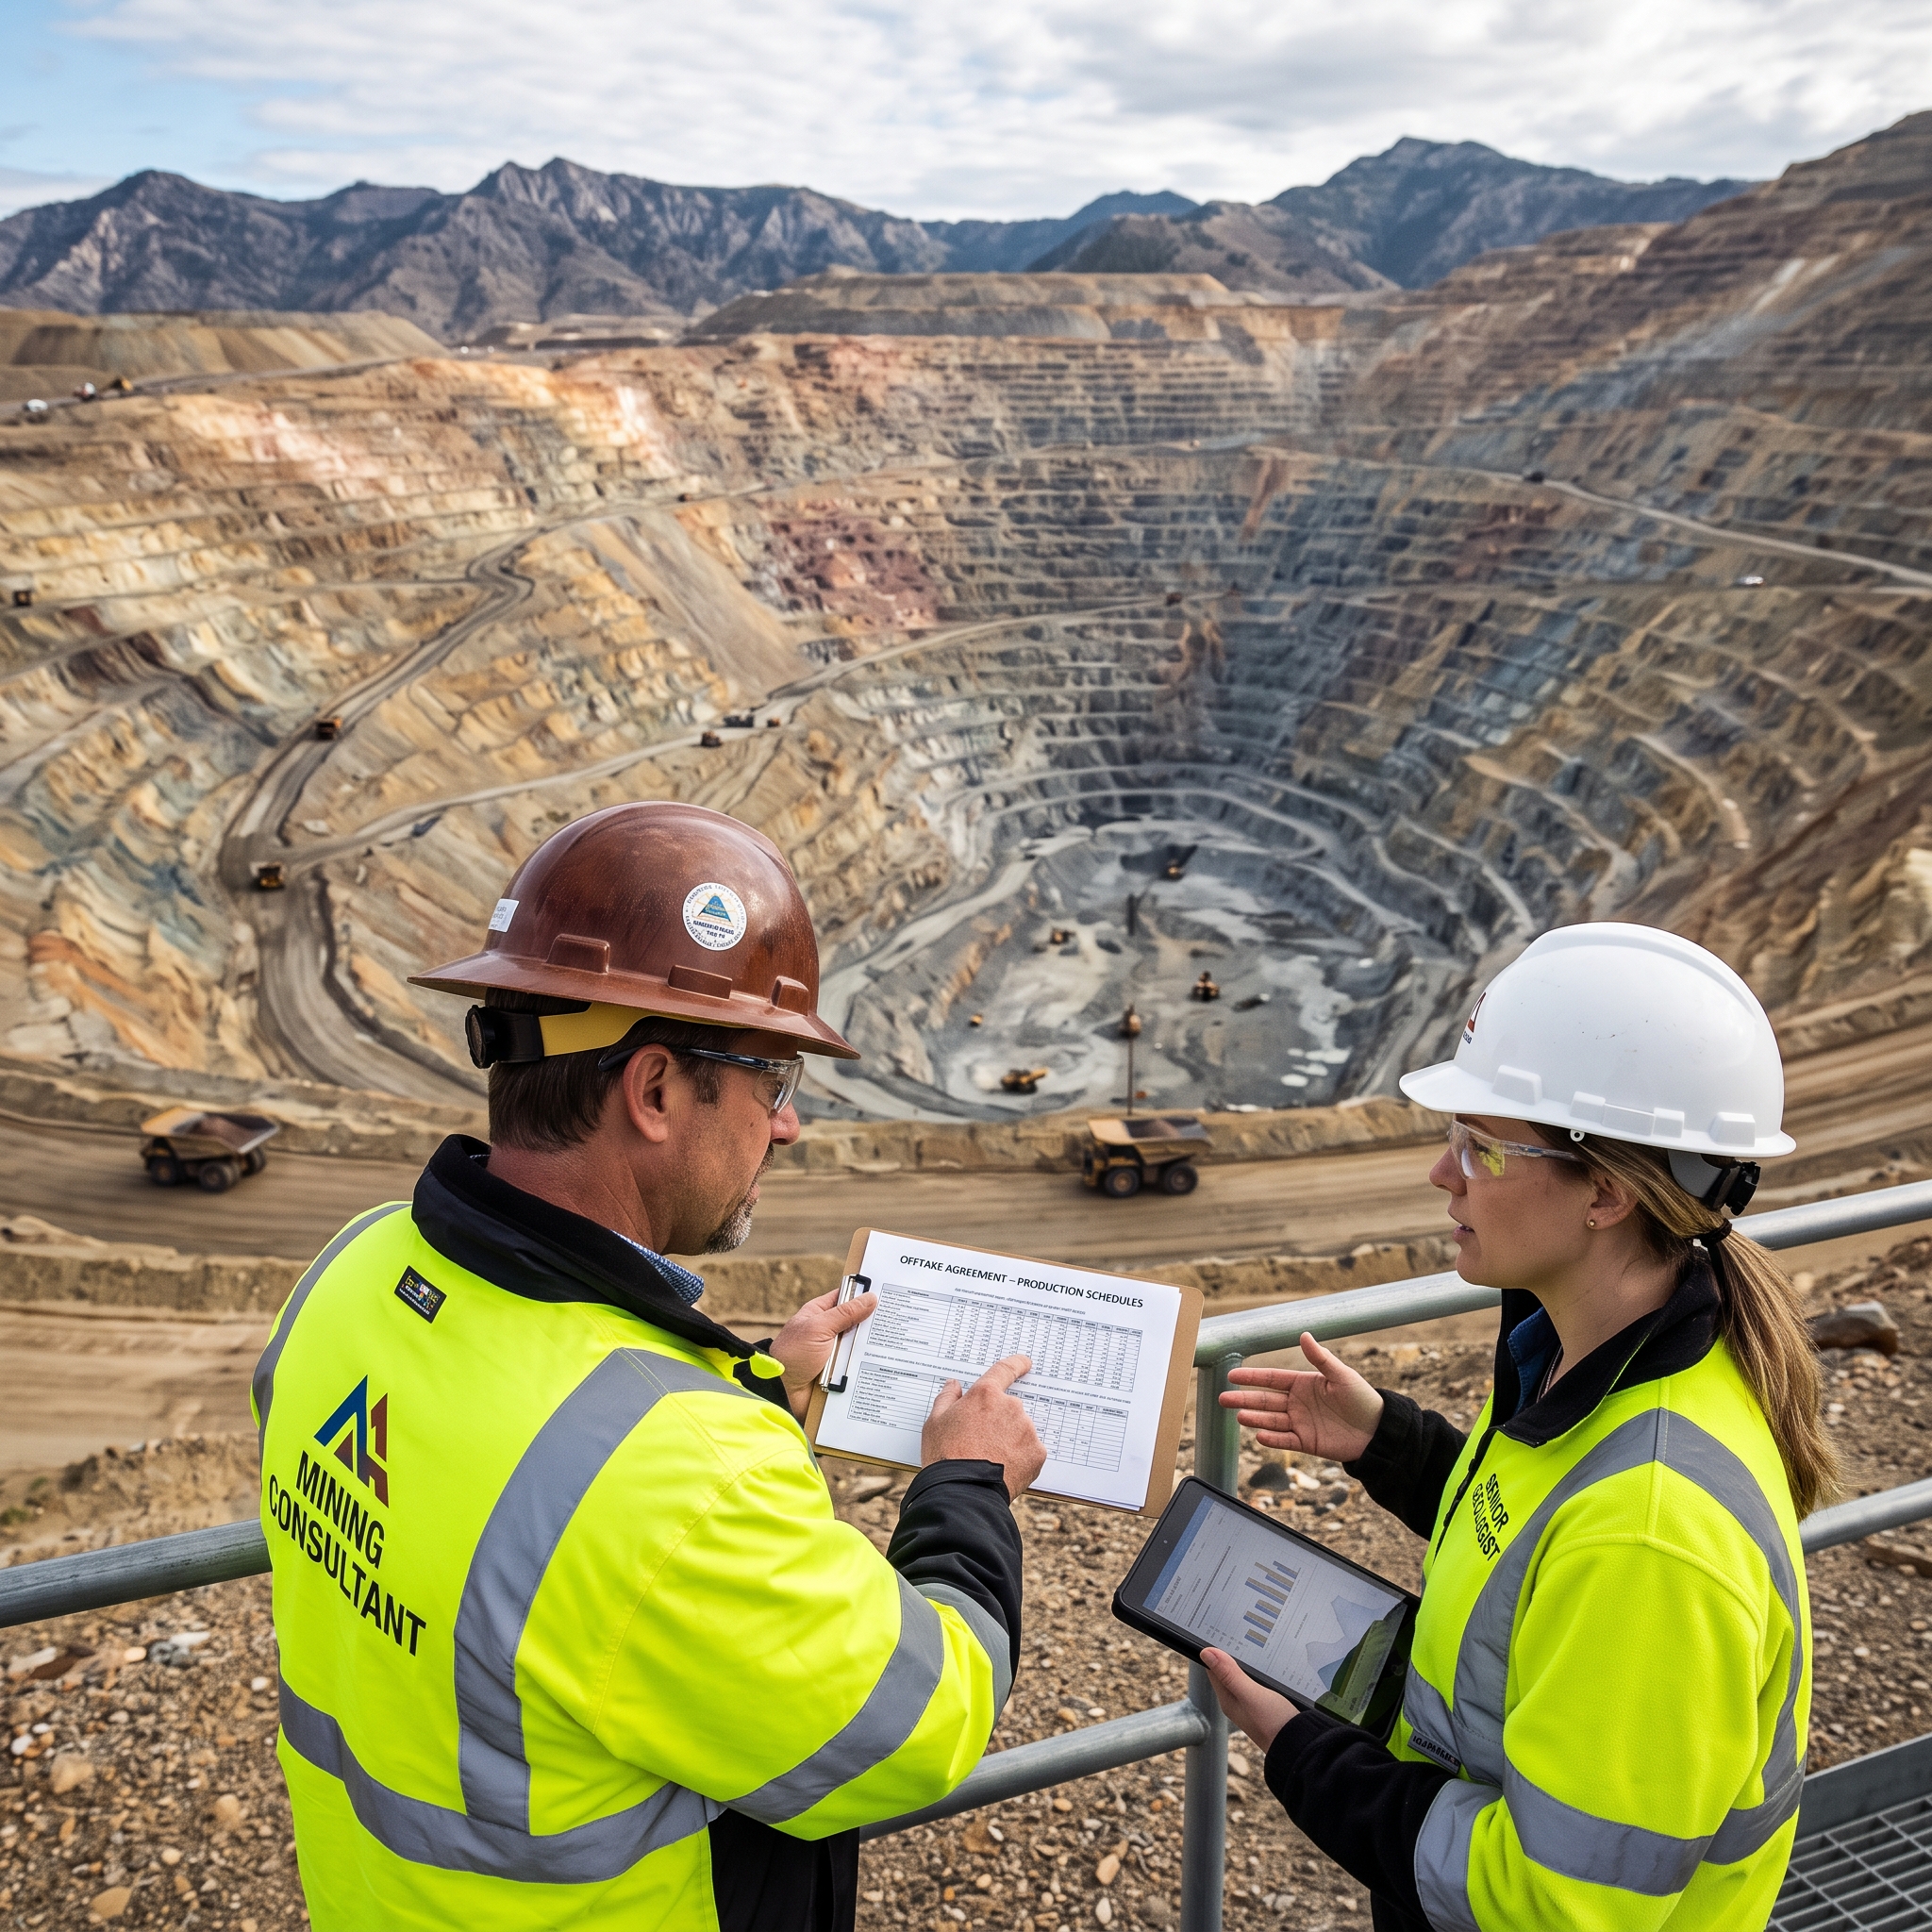


Contractual arrangements are crucial for the successful implementation of project finance. Offtake deals are basic contracts where the buyer agrees to purchase the output of the project. Distadio and Ferguson (2024) note that offtake agreements are strategic alliances, through which both the demand and finance are secured. Though financial certainty is required in debt funding, it limits the financing flexibility of the project – its capability to raise further debts or restructure capitals. Therefore, the right balance between these two elements should be found.
Project finance flexibility and bankability require strategic volume commitments. The lenders make use of nonfinancial contracts to manage their risks, influencing the capital structure (Corielli et al., 2010). Thus, committing all the project’s capacity in the long term does not allow for capturing upside potential of the market. A possible solution is the usage of step-down volume commitments – to make commitments for high capacities during the period of debt repayment and reduce them later in order to pay the debt while retaining some capacity for future financing or spot selling.
Pricing strategies need to avoid project being stuck in unfavorable financing conditions. Fixed pricing strategy guarantees certain price but exposes the projects to inflation risk, thus making it inflexible. In order to solve this problem, it is necessary to negotiate with developers to establish hybrid pricing strategies, including floor-and-ceiling mechanisms. These mechanisms will protect the downside risk of the initial lenders, while allowing the sponsors to benefit from the favourable market trend.
The management of exclusivity is another critical aspect. In many cases, off-takers demand a right of first refusal (ROFR) on any uncontracted output. However, strict ROFRs make it difficult for a sponsor to bring in new equity investors who might want off-take rights. Therefore, it is recommended that sponsors keep their options open by negotiating very specific exclusivity. In case ROFRs are necessary, they should be very strict in terms of time to ensure that the project company is able to switch to different offtakers and investors without needing the consent from the first offtaker.
The step-in rights of the lender and change-of-control clause affect the future possibility of capital restructure to a great extent. The off-take agreement reduces flexibility if there are stiff change-of-control clauses where the off-taker has the right to terminate the contract if there are any sales of equity. It is important to ensure that flexibility is maintained with exceptions to the situation involving project financing. This would enable the contract to remain assignable to the lender without terminating it.
Off-take agreements although essential for raising the initial capital of a project cannot prevent future financial strategies. Considering them as dynamic alliances (Distadio & Ferguson, 2024) and as risk transfer instruments (Corielli et al., 2010) allows sponsors to meet their lender demands. Step-down volumes, hybrid pricing, restricted exclusivity and assignable contracts help sponsors to ensure certainty in revenue without reducing flexibility in the future.
References
Corielli, F., Gatti, S., & Steffanoni, A. (2010). Risk Shifting through Nonfinancial Contracts: Effects on Loan Spreads and Capital Structure of Project Finance Deals. Journal of Money, Credit and Banking, 42(7), 1295–1320. https://doi.org/10.1111/j.1538-4616.2010.00342.x
Distadio, L. F., & Ferguson, A. (2024). Mine Offtake Contracting, Strategic Alliances and the Equity Market. SSRN Electronic Journal. https://doi.org/10.2139/ssrn.4752396