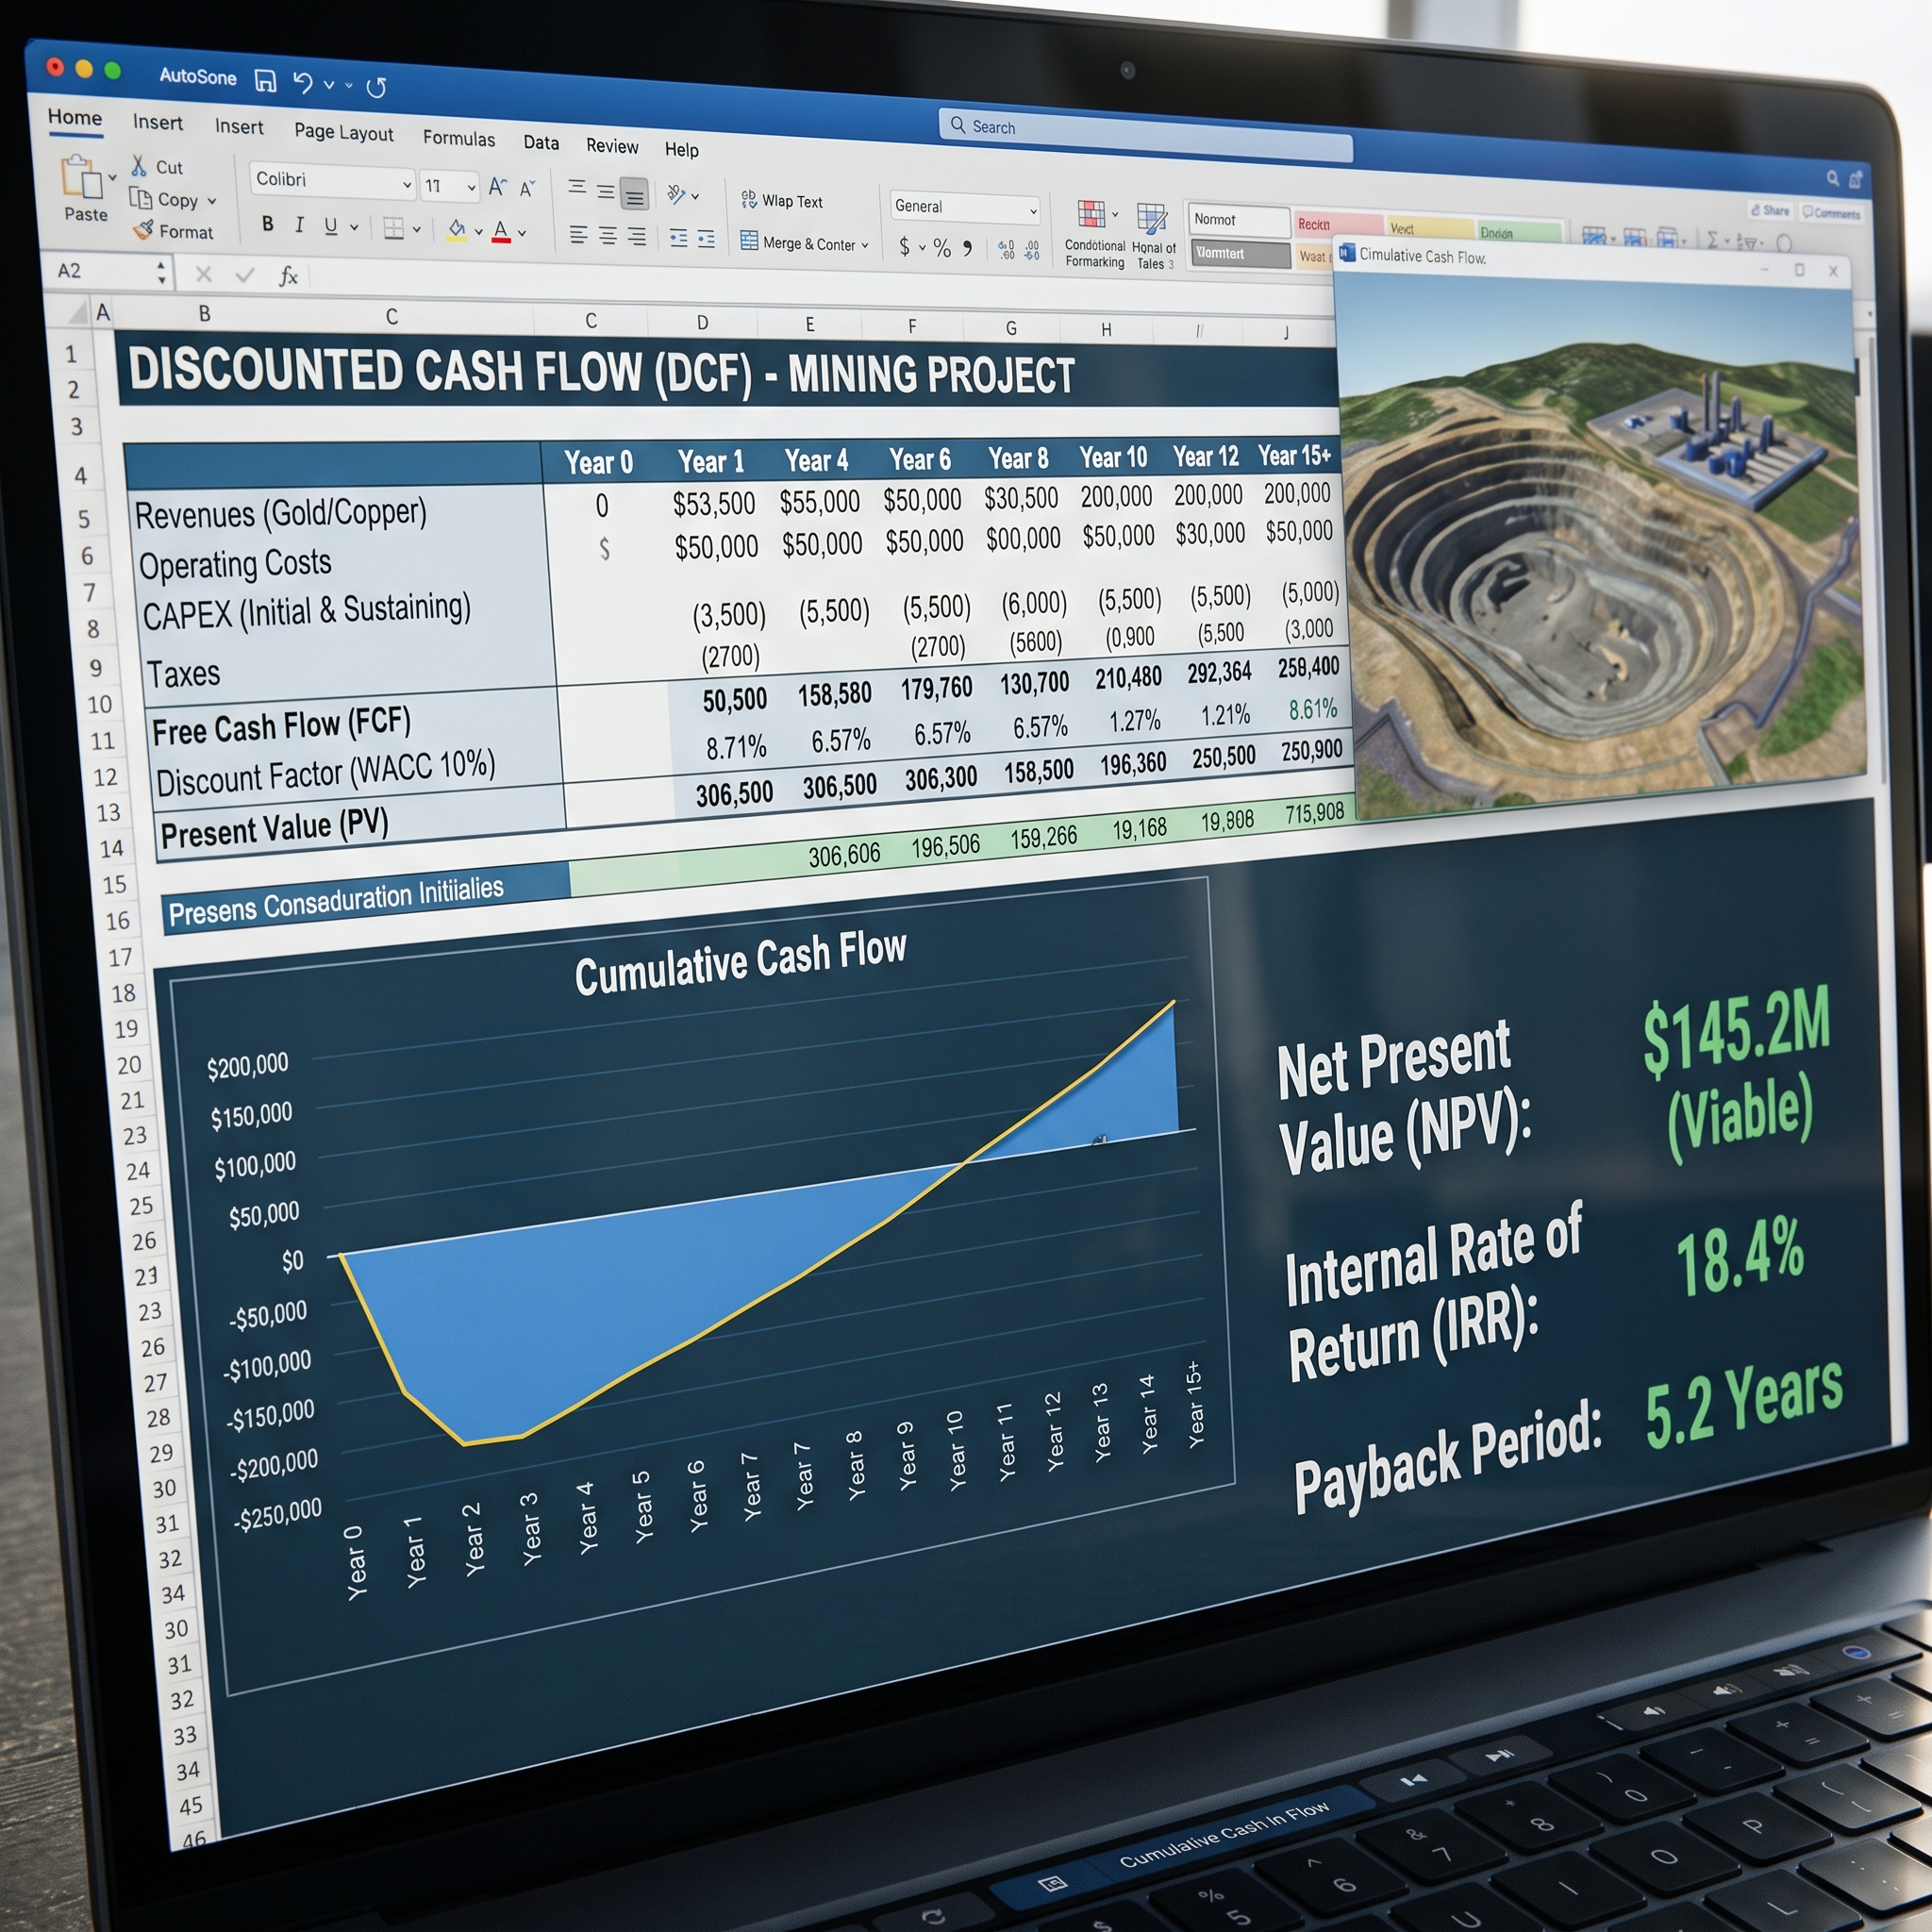


Capital investments in resource extraction ventures are substantial and require years of development before positive cash flow begins. An evaluation of whether a mineral deposit justifies capital allocation requires converting uncertain future production into present-day economic value. Discounted Cash Flow (DCF) analysis serves as the primary financial tool to evaluate mine feasibility by forecasting life-of-mine cash flows and discounting them to reflect the time value of money and project risk (Topal, 2008; Mirakovski et al., 2010).
Mineral project cash flow estimation begins with annual revenue forecasts derived from ore tonnage, head grade, process recovery rates, and long-term commodity prices (Dwitiandi, 2007; Lattanzi, 2010). Capital expenditure (CAPEX) projections incorporate initial pre-production infrastructure alongside sustaining capital required across operational years (Ayuningtyas & Nainggolan, 2026). Operational expenditures (OPEX), site administration, smelting charges, government royalties, and reclamation costs are subtracted from gross revenues (Krisna & Faturohman, 2021). The resulting net free cash flow profile details annual monetary movements over the entire mine life.
Financial viability hinges on key indicators derived from discounted cash flow schedules (Kadji, 2025). Net Present Value (NPV) measures the difference between discounted cash inflows and initial capital outflows. A positive NPV indicates that the venture creates economic value above its cost of capital (Damodaran, 2012). The Internal Rate of Return (IRR) identifies the discount rate at which NPV equals zero, offering a direct metric of profitability (Gitman & Zutter, 2015). The Discounted Payback Period (DPP) calculates the years needed to recover initial investments with interest. Corporate analysts typically determine the discount rate using the Weighted Average Cost of Capital (WACC) or risk-adjusted rates reflecting market and project uncertainties (Ovalle, 2020).
Project profitability exhibits far higher sensitivity to commodity price and ore grade variations than to internal operating cost fluctuations (Guj, 2006; Dwitiandi, 2007). Traditional DCF models apply a single risk-adjusted discount rate across all net cash flows, treating controllable operating costs and volatile sales revenues uniformly (Krisna & Faturohman, 2021). Analysts frequently complement standard DCF modeling with sensitivity analysis, Monte Carlo simulation, and Real Options Valuation (ROV) to evaluate market fluctuations and operational flexibility (Topal, 2008; Ayuningtyas & Nainggolan, 2026).
Discounted Cash Flow analysis remains the fundamental cornerstone of mine feasibility studies by converting complex geological and engineering parameters into quantitative financial metrics. The combination of DCF models with probabilistic risk simulation allows executives and investors to make informed capital allocation decisions amidst market uncertainty.
References
Ayuningtyas, M., & Nainggolan, Y. A. (2026). The Feasibility Study of A8 Pit Project in PT XYZ. Jurnal Locus: Penelitian & Pengabdian, 5(9), 7631–7642.
Damodaran, A. (2012). Investment Valuation: Tools and Techniques for Determining the Value of Any Asset (3rd ed.). John Wiley & Sons.
Dwitiandi, D. (2007). Marginal Gold Project Decision with Discounted Cash Flow (DCF) Method. Proceedings Joint Convention Bali 2007, 32nd HAGI, 36th IAGI, and 29th IATMI.
Gitman, L. J., & Zutter, C. J. (2015). Principles of Managerial Finance. Pearson Education.
Guj, P. (2006). Mineral project evaluation – An introduction. In P. Maxwell & P. Guj (Eds.), Australian Mineral Economics (Chapter 10). AusIMM.
Kadji, R. (2025). Economic Feasibility Analysis of Mining Business Plan CV. XYZ, Golopongkor Village, Komodo District, West Manggarai Regency. International Journal of Environmental, Sustainability and Social Science, 6(5), 925–931.
Krisna, O. S., & Faturohman, T. (2021). Economic Analysis of Coal Mining Project Using Real Option Valuation Method. Review of Integrative Business and Economics Research, 10(3), 450–469.
Lattanzi, C. R. (2010). Valuation of Metals and Mining Companies / Discounted Cash Flow Analysis Input Parameters and Sensitivity. Canadian Institute of Mining, Metallurgy and Petroleum (CIM).
Mirakovski, D., Krstev, B., Krstev, A., & Petrovski, F. (2010). Mine Project Evaluation Techniques. University Goce Delcev, Faculty of Natural & Technical Sciences.
Ovalle, A. (2020). Analysis of the discount rate for mining projects. MassMin2020, Australian Centre for Geomechanics, 1–14.
Topal, E. (2008). Evaluation of a mining project using Discounted Cash Flow analysis, Decision Tree analysis, Monte Carlo Simulation and Real Options using an example. International Journal of Mining and Mineral Engineering, 1(1), 62–76.