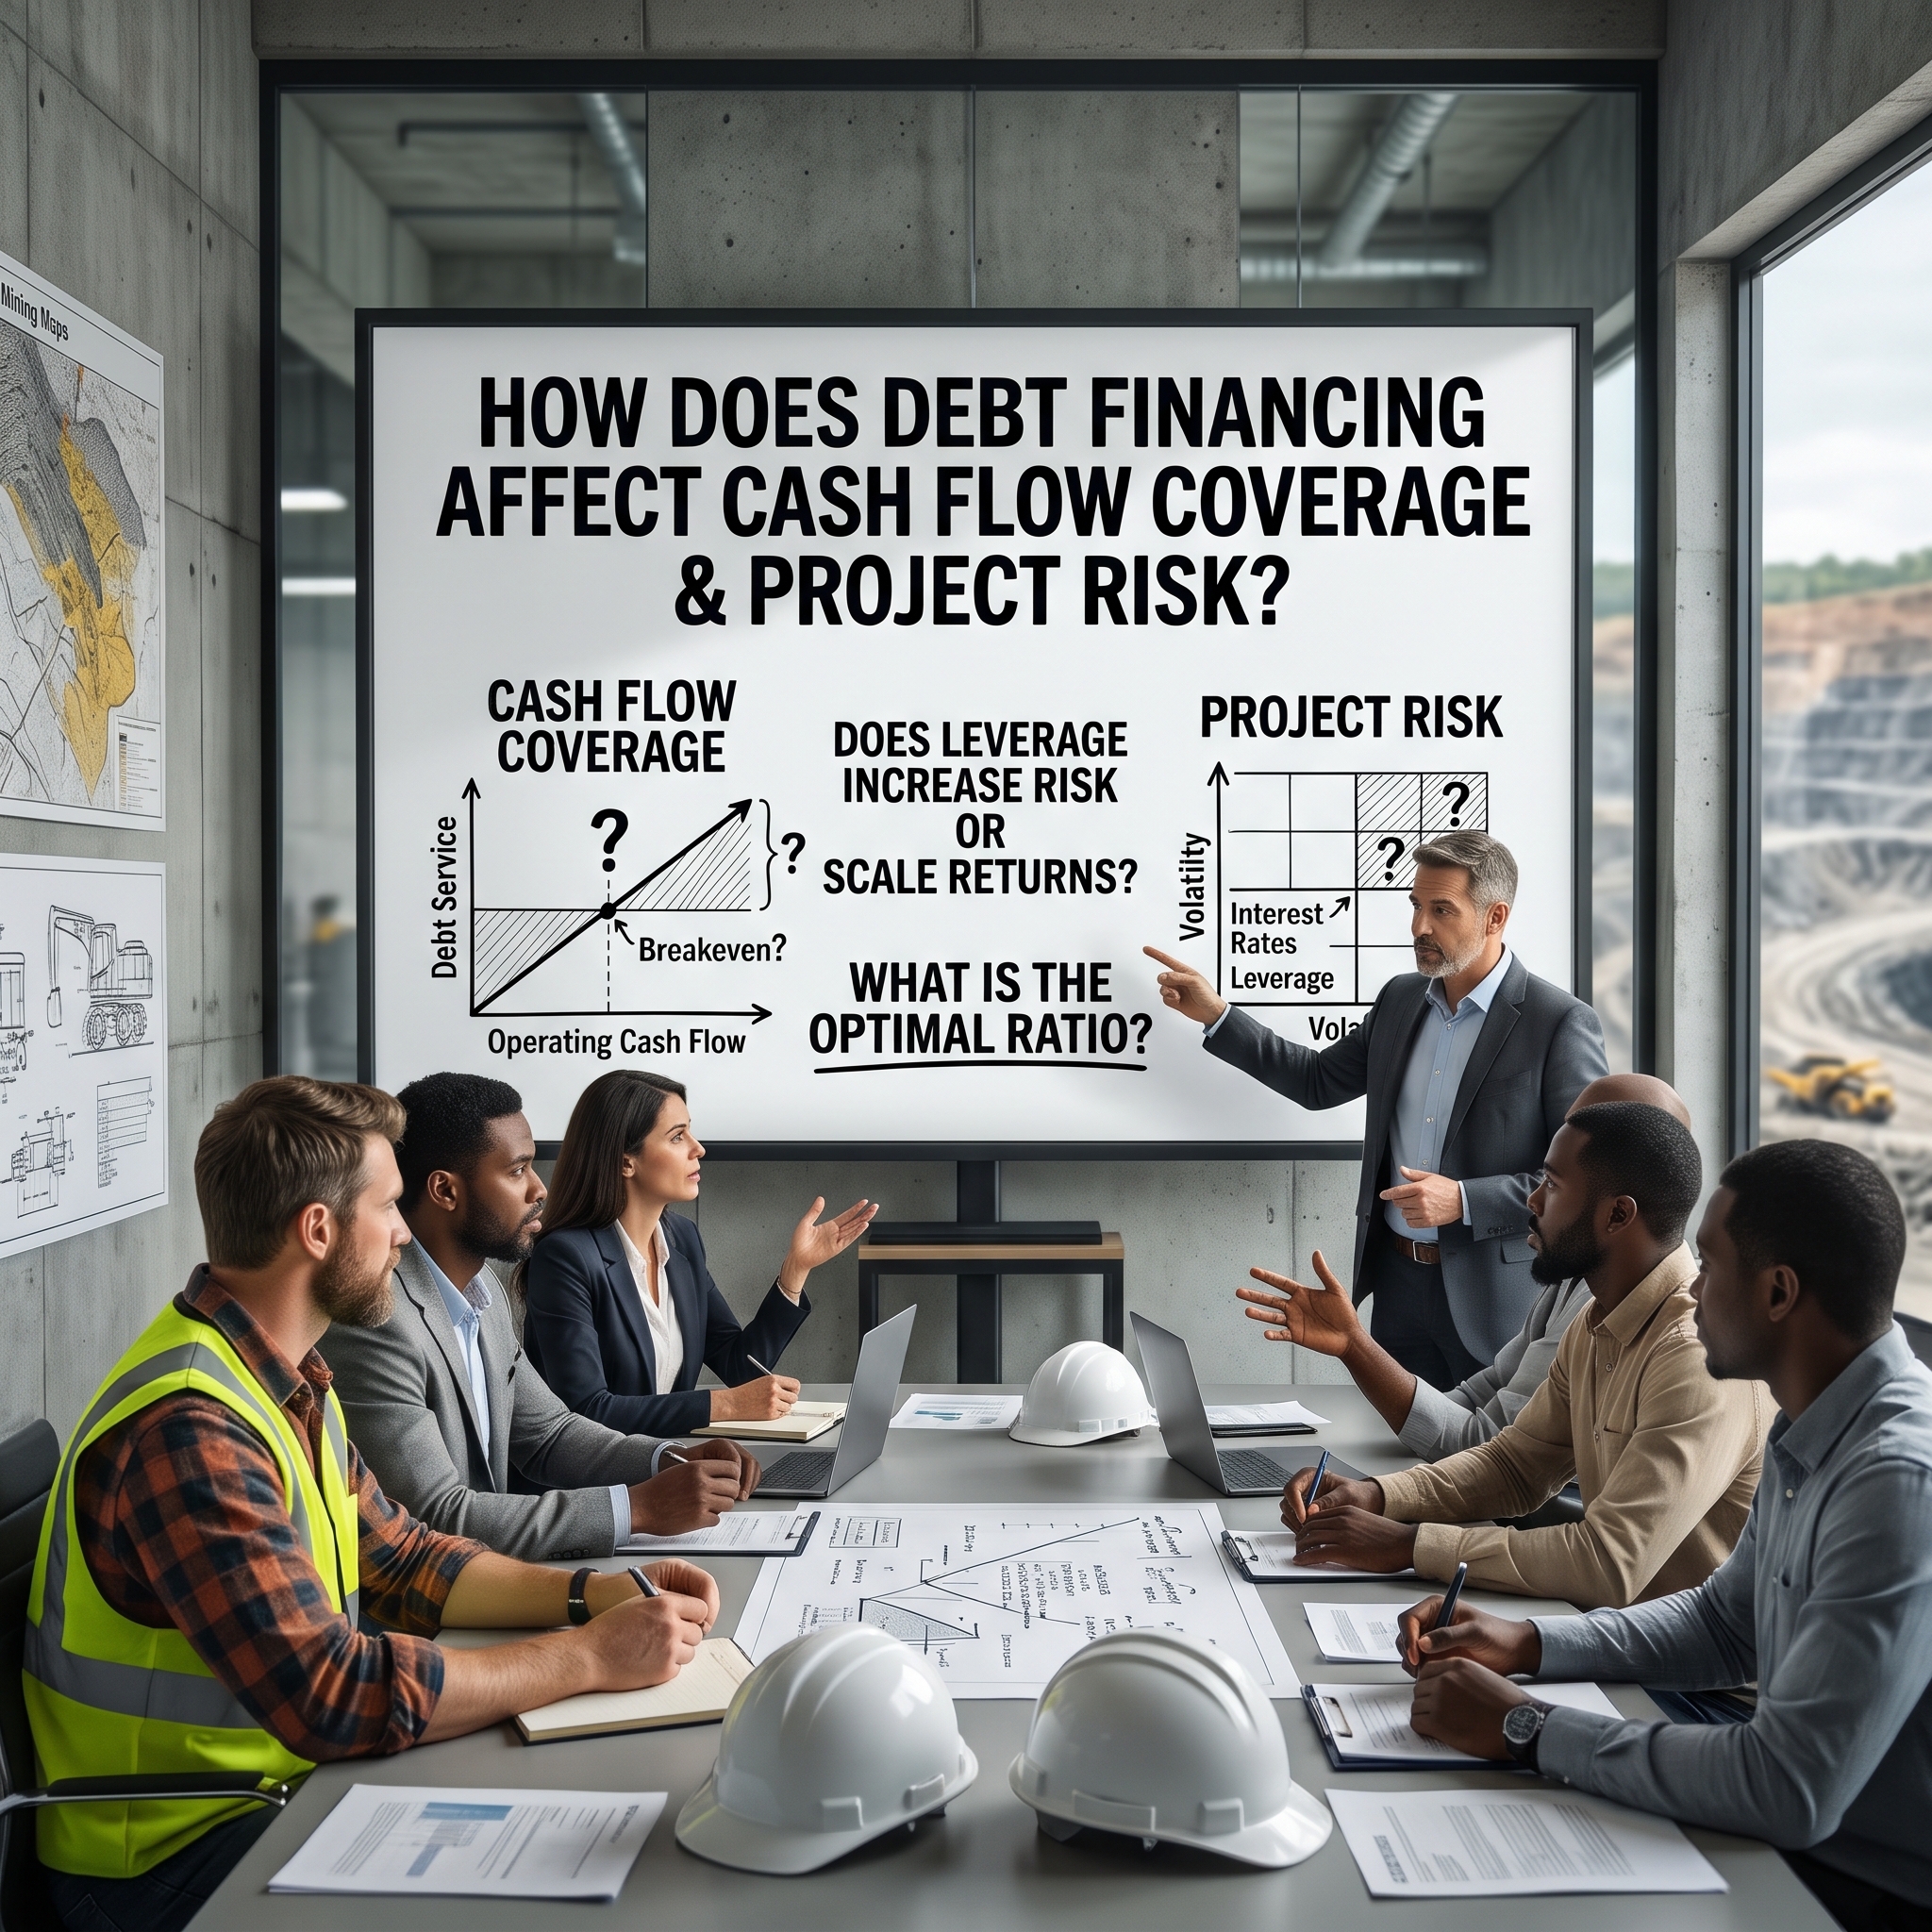


Debt financing represents a critical instrument for funding capital-intensive ventures, yet it permanently alters a project’s financial risk profile. Borrowed capital enables equity sponsors to fund ambitious ventures and enhance return on equity, but debt obligations impose rigid repayment schedules that senior lenders enforce without regard to operating conditions. Unlike corporate balance-sheet borrowing, project finance relies solely on cash generated by dedicated project assets to satisfy debt service. Consequently, high debt levels compress the operational safety buffer between cash receipts and contractually mandated loan repayments. When leverage increases, debt service coverage narrows, leaving project cash flows vulnerable to market shocks and technical default.
Debt financing directly constrains cash flow coverage by introducing non-negotiable principal and interest charges into project operations. Standard corporate earnings metrics such as EBITDA often inflate perceived liquidity because they overlook working capital adjustments, sustaining maintenance capital expenditures, and mandatory tax outlays. Project financiers therefore size debt facilities strictly against cash flow available for debt service, known as CFADS. Senior lenders calibrate total borrowing capacity against the minimum debt service coverage ratio projected during the venture’s single most fragile operational period. Furthermore, financial engineers utilize debt sculpting to shape loan amortization schedules directly around seasonal revenue curves, ensuring debt service matches operational cash realization rather than arbitrary flat payments.
High debt levels significantly increase financial risk if a project’s revenue falls short of projections. Unexpected disruptions; such as price cuts, delayed payments from buyers, or economic downturns, can quickly wipe out thin cash buffers and cause severe liquidity crises. This risk is particularly high for projects with unstable income and few physical assets to back up the loans. Furthermore, over-borrowing becomes highly dangerous when the debt exceeds the actual value of the project’s assets. In a default scenario where debt is higher than the asset liquidation value, lenders will take immediate losses, and the heavy debt burden will deter sponsors from investing new equity.
Lenders construct elaborate defensive frameworks within credit agreements to insulate project cash flows against default. Credit agreements establish multi-tiered covenant thresholds, including mandatory minimum coverage floors alongside distribution lock-up ratios that freeze dividend distributions whenever operational performance weakens. Historical coverage benchmarks monitor gradual revenue deterioration over multi-quarter horizons to enforce early interventions. Additionally, loan structures require dedicated debt service reserve accounts that hold up to six months of forward-looking principal and interest. These liquid reserves allow project companies to survive temporary disruptions without triggering acceleration. Complementary layers of subordinated debt can also absorb operational shortfalls, preserving enterprise value and preventing premature liquidation.
Debt financing fundamentally transforms project operations by exchanging financial flexibility for leverage-driven returns. Heavy borrowing tightens cash flow coverage, amplifies operational vulnerabilities, and penalizes inaccurate revenue forecasts. Successful project structuring does not depend on maximising leverage, but on aligning debt service commitments with verifiable cash generation and realistic asset values. Thorough risk mitigation requires disciplined cash flow modeling, defensive covenant cushions, and dedicated liquidity reserves that protect project solvency across volatile economic cycles. Ultimately, a balanced capital structure preserves long-term project viability by maintaining sufficient operational cash buffers to endure unforeseen disruptions.