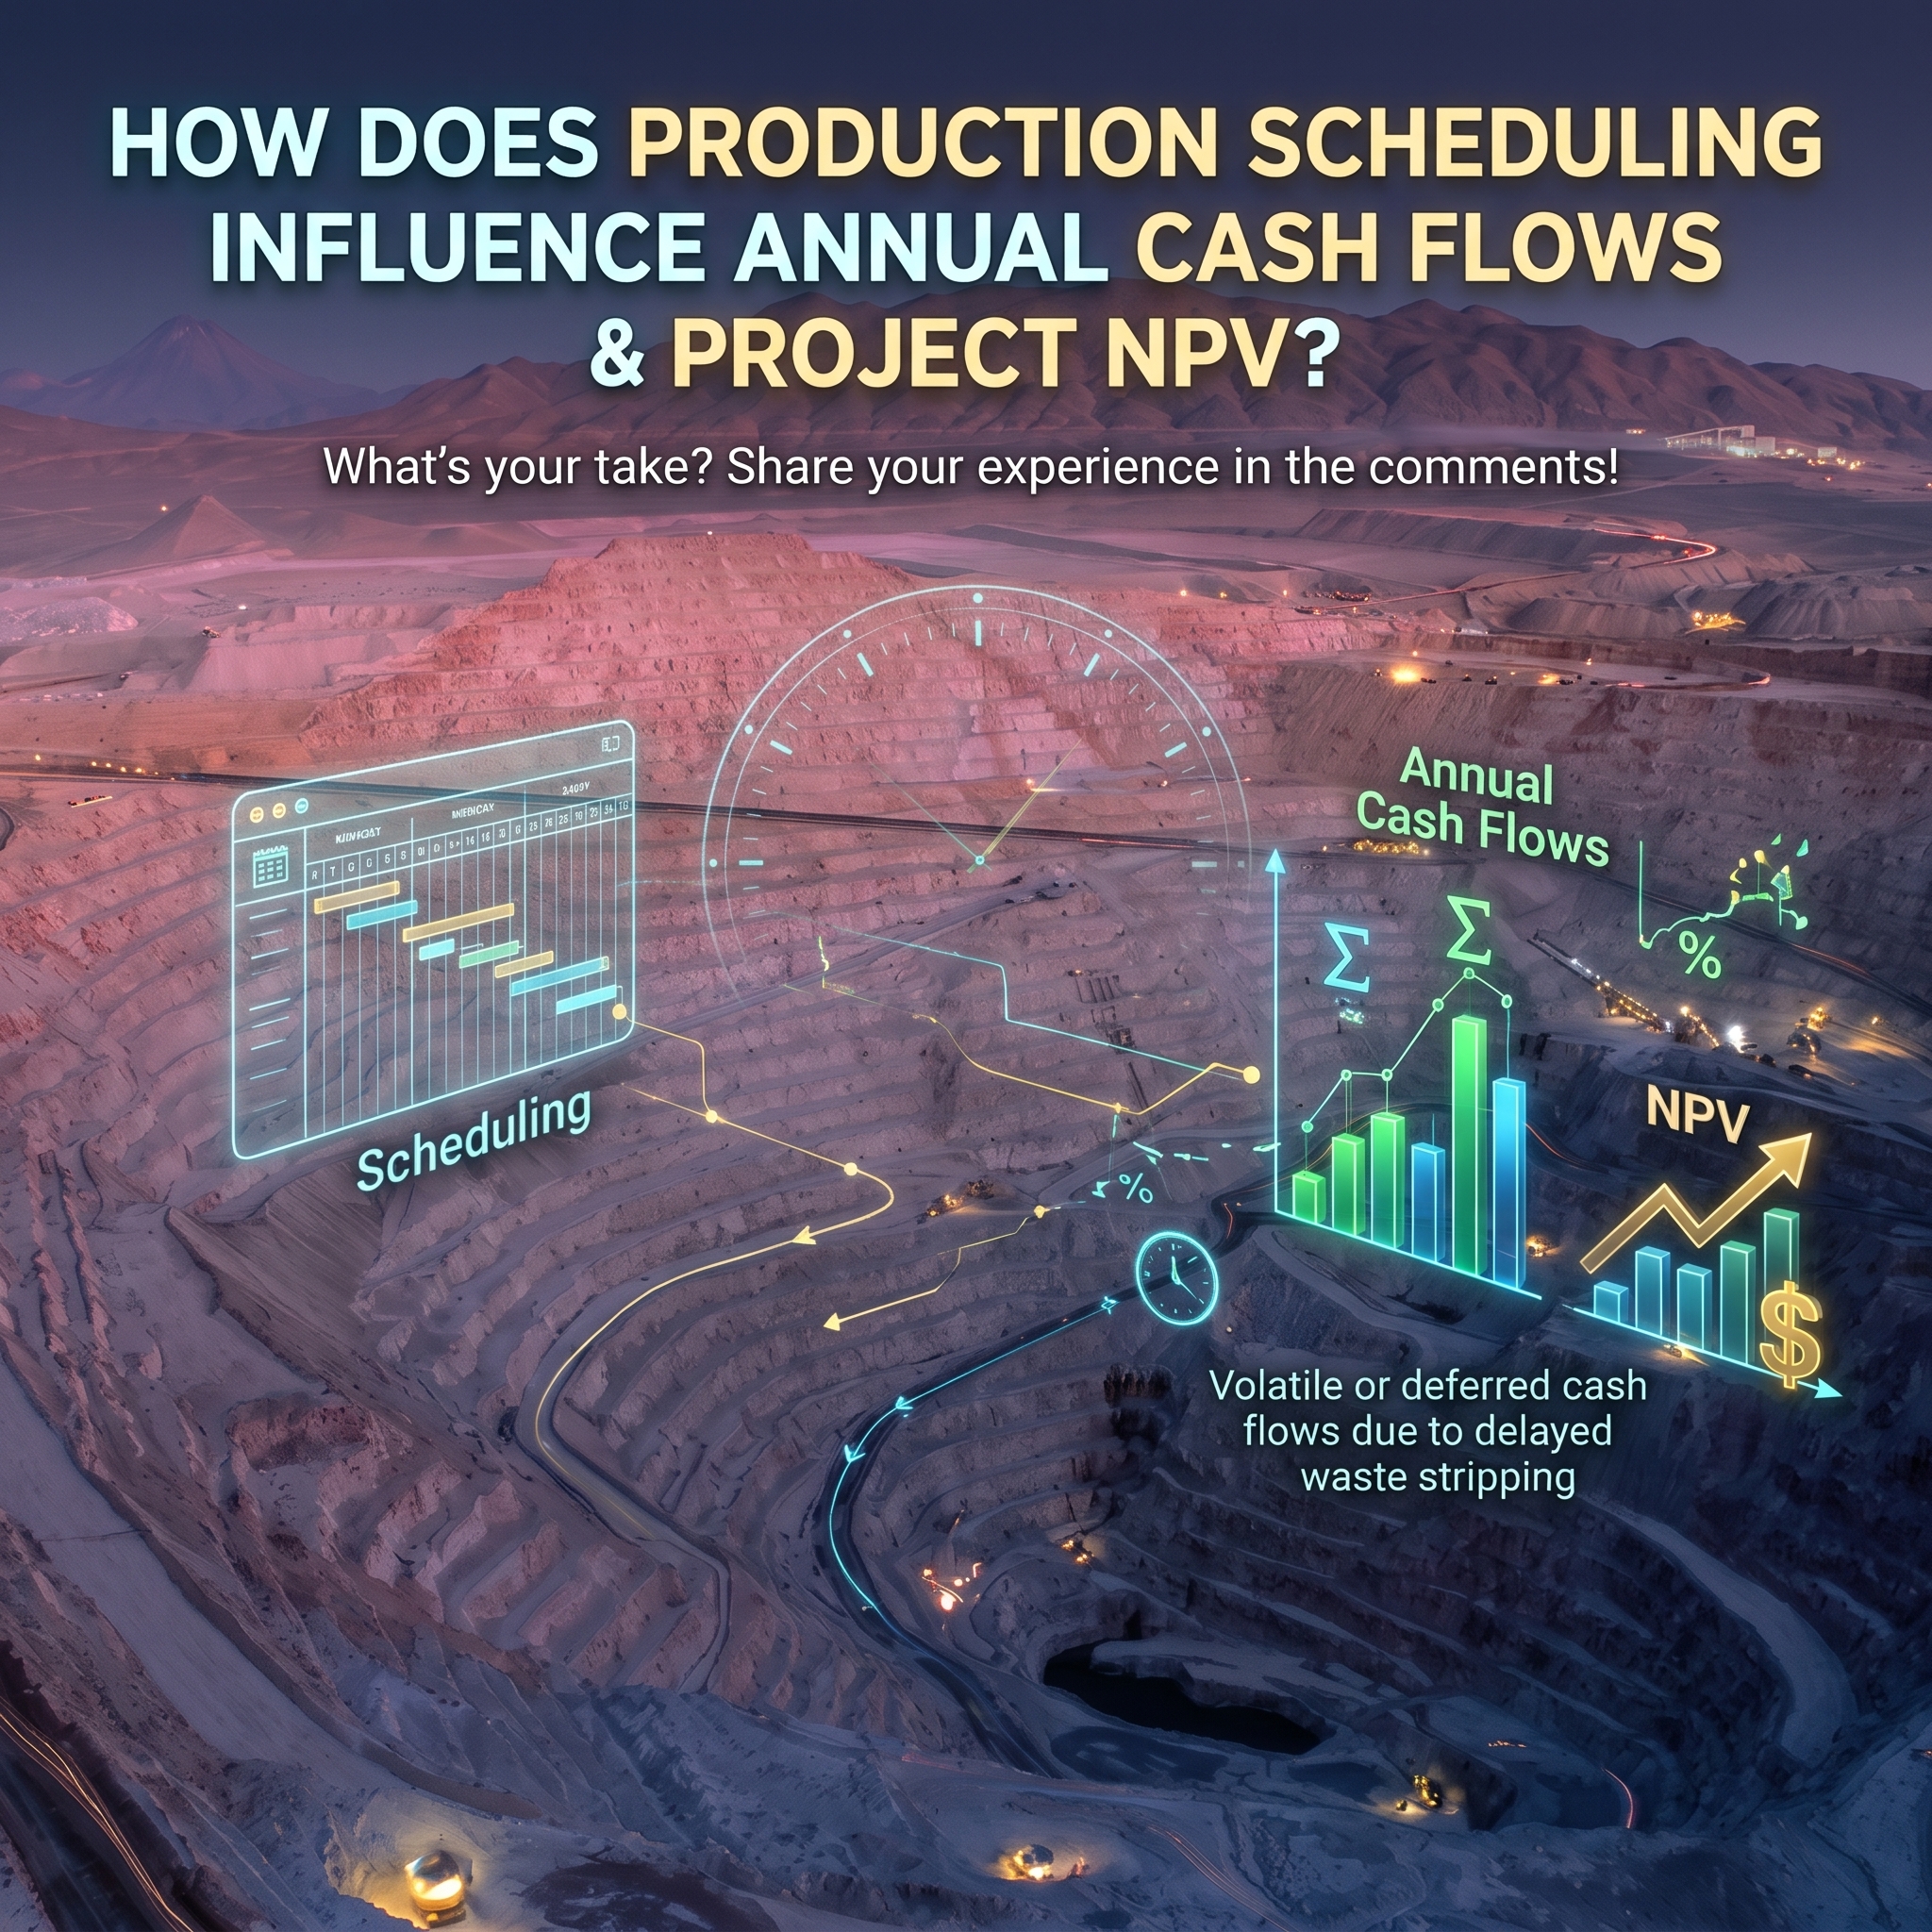


Factory production planning is frequently treated as a routine shop-floor coordination exercise, yet operating timelines fundamentally dictate corporate liquidity. Decisions regarding when specific tasks begin and conclude determine the exact calendar dates when capital is committed and when client revenues materialize. Because capital carries an inherent opportunity cost, operational schedules directly shape annual net cash flows and long-term project Net Present Value. A well-structured production schedule acts as an indispensable financial lever. It aligns physical assembly with capital requirements, curtails balance sheet bloat, and safeguards overall investment returns.
Financial valuation relies on the time value of money, which dictates that cash received today carries greater economic worth than an identical amount received in future operating cycles. Project Net Present Value discounts every anticipated cash inflow and outflow back to the present baseline using a predetermined discount rate. Mathematical project scheduling models demonstrate that corporate value reaches its peak when revenue-generating milestones occur as early as possible while expenditure disbursements are postponed to the latest permissible dates. Early completion of deliverable project phases accelerates substantial cash receipts into earlier annual reporting periods. Conversely, delaying raw material purchases and supplier payouts until tasks strictly require them preserves liquidity on the corporate balance sheet. This temporal discipline shortens the capital payback window, lowers compounding discount penalties, and enhances cumulative project returns.
Physical inventory represents one of the largest drains on working capital across manufacturing operations. Inefficient production schedules frequently create manufacturing bottlenecks that cause work-in-process inventory to sit idle on shop floors. Idle materials lock up critical cash reserves without yielding immediate commercial returns. The cash conversion cycle measures the elapsed timeframe between paying for raw inputs and collecting cash from customer invoices. Lean scheduling frameworks, smaller batch sizes, and synchronized material deliveries compress this metric by decreasing days inventory outstanding. Faster processing velocity turns dormant stock into liquid receivables and eliminates unnecessary warehouse holding expenses. Reduced carrying costs and rapid inventory turnover directly expand annual operating cash flows, providing firms with fresh liquidity to reinvest without requiring expensive external debt.
Uncertainty remains an unavoidable reality in modern industrial production. Unexpected equipment breakdowns, supply chain disruptions, and stochastic task durations routinely threaten planned project timelines. Unplanned project delays postpone downstream revenue milestones while fixed overhead expenses and variable holding costs continue to accumulate, which sharply erodes expected Net Present Value. Modern production frameworks employ adaptive scheduling algorithms and deep reinforcement learning models to adjust operational timelines dynamically in response to shop-floor disruptions. Rather than relying on rigid, overly conservative buffers that artificially depress projected project value, these adaptive policies continuously optimize task start times. Regular sensitivity analyses across discount rates, material inflation, and duration variances further enable corporate leaders to stress-test financial projections and insulate annual cash flows against extreme operational volatility.
Production scheduling forms the vital operational bridge between daily workshop activities and overarching corporate financial performance. Strategic timing of cash transactions, rapid inventory throughput, and proactive schedule risk management allow industrial firms to preserve operating liquidity and maximise project asset value. Enterprise leaders must treat master production schedules as core financial strategies rather than isolated logistical plans.